The 50/30/20 Budget Rule: How It Works, Examples, and How to Make It Fit Your Life
The 50/30/20 budget rule is a simple way to organize your take-home income into three broad priorities: needs, wants, and savings or debt repayment. Learn exactly how the rule works, what belongs in each category, how to calculate your numbers, what to do when your budget does not fit the percentages, and how to adapt the method to your real financial situation.
What is the 50/30/20 budget rule?
The 50/30/20 budget rule is a budgeting framework that uses take-home income as the starting point and divides it into three broad categories:
Essential expenses that support basic living and financial obligations.
Optional or lifestyle spending that improves comfort or enjoyment.
Savings, future goals and additional debt repayment beyond required minimums.
What Is the 50/30/20 Budget Rule?
The 50/30/20 budget rule is a simple budgeting framework designed to help you divide your take-home income among three broad financial priorities: needs, wants, and savings or debt repayment.
Instead of asking you to create dozens of individual spending categories, the method gives you three large buckets. The basic guideline is to use about 50% of your after-tax income for needs, about 30% for wants, and about 20% for savings and debt-related goals.
That simplicity is one of the biggest reasons the method remains useful. A budget can become difficult to maintain when every purchase requires a complicated classification. The 50/30/20 approach gives you a broader framework that can be understood quickly and reviewed regularly.
The method should not, however, be treated as a test that determines whether you are financially successful. Your circumstances may make the exact percentages unrealistic. Someone paying very high housing costs, supporting children, managing significant debt or living on a low income may need a different allocation.
Think of 50/30/20 as a starting framework. Its value is that it gives you a way to look at your money, identify where it is going and decide whether your current spending reflects your priorities.
How Does the 50/30/20 Budget Rule Work?
The first step is to determine your monthly take-home income. This is generally the amount available to you after taxes and other required payroll deductions that are already removed from your paycheck.
Once you know your take-home income, multiply it by each percentage.
For example, suppose your monthly take-home income is $4,000.
The goal is not necessarily to spend exactly $2,000, $1,200 and $800 every month. Instead, these amounts give you reference points. You can compare your actual spending with the framework and determine where adjustments may be useful.
What Counts as Needs in the 50/30/20 Budget?
The 50% category is designed for expenses that are necessary for basic living, maintaining essential responsibilities or meeting important financial obligations.
Needs are generally expenses that would be difficult or harmful to eliminate. They are different from purchases that are enjoyable but optional.
Common examples of needs
- Housing or a basic place to live
- Essential utilities
- Groceries and necessary food
- Basic transportation
- Required insurance
- Essential medical expenses
- Childcare required for work or essential responsibilities
- Minimum required debt payments
- Basic clothing and household necessities
- Other expenses that are genuinely necessary for your situation
Needs are not the same as everything you normally buy
One of the most important parts of using the 50/30/20 rule correctly is distinguishing a genuine need from a preferred version of a need.
For example, transportation may be a need if you must travel to work. But an expensive vehicle with a large monthly payment may be a choice rather than an unavoidable requirement.
Housing can also illustrate the difference. Having somewhere to live is a need. Paying for a much larger home than necessary because you prefer the extra space may involve both need and lifestyle choice.
What if my needs are more than 50%?
This is one of the most common problems people encounter with the framework.
If your essential expenses consume 60%, 70% or even more of your take-home income, that does not mean you have failed at budgeting. It means your current cost structure does not fit the traditional guideline.
You can temporarily reduce the wants category and direct more income toward essential expenses. You can also examine whether housing, transportation, insurance, debt payments or other major fixed costs can be reduced over time.
The important thing is to recognize the difference between a temporary imbalance and a structural problem. If essential expenses remain far above 50% for a long period, changing the percentages alone may not solve the underlying issue.
What Counts as Wants in the 50/30/20 Budget?
Wants are expenses that improve comfort, convenience, entertainment or lifestyle but are not generally essential to maintaining basic living.
This category matters because a realistic budget should not assume that every dollar must be directed toward survival or long-term financial goals. People need room for enjoyment too.
Examples of wants
- Restaurant meals and takeout
- Entertainment
- Streaming subscriptions
- Hobbies
- Travel and vacations
- Non-essential shopping
- Premium versions of products or services
- Leisure activities
- Some convenience spending
- Other discretionary lifestyle purchases
Why the wants category matters
It can be tempting to build a budget that cuts every optional expense. The problem is that a plan that removes all enjoyment may be difficult to maintain.
The 30% category creates a deliberate place for discretionary spending. Instead of wondering whether every enjoyable purchase is financially irresponsible, you can decide how much lifestyle spending fits within your broader plan.
Of course, the 30% figure is not permission to spend money simply because it is available. If you have expensive debt, no emergency reserve or a major financial goal, you may decide that less than 30% should go toward wants.
What Counts as Savings and Debt in the 50/30/20 Rule?
The final 20% is focused on building financial security, funding future goals and making progress on debt beyond required minimum payments.
This category is particularly important because it is the part of today's income that can strengthen tomorrow's financial position.
Examples of savings and future-focused goals
- Emergency savings
- Retirement contributions
- Long-term investments
- Short-term savings goals
- Education savings
- Large planned purchases
- Additional debt repayment
- Other intentional financial goals
Minimum debt payments versus extra debt payments
A useful distinction is between required minimum payments and additional debt repayment.
Required minimum payments are generally treated as essential obligations because failing to make them can lead to serious financial consequences.
Additional payments made specifically to accelerate debt reduction can be considered part of the future-focused portion of the framework.
This distinction can help you understand what your budget is actually doing. A household might appear to be putting 20% toward its future, but if nearly all of that amount is consumed by required minimum payments, its long-term savings capacity may still be limited.
Should the 20% go entirely to savings?
Not necessarily.
Your priorities should depend on your circumstances. Someone with no emergency reserve may prioritize building cash savings. Someone carrying very expensive debt may direct more toward repayment. Someone who already has a strong cash reserve may focus more heavily on long-term investing or retirement.
The important principle is to make the 20% intentional rather than allowing it to disappear into unplanned spending.
50/30/20 Budget Categories: What Goes Where?
The hardest part of the 50/30/20 rule is often not the mathematics. It is deciding where individual expenses belong.
Some expenses are obvious. Others depend on your circumstances. Instead of trying to create a perfect universal classification, consider whether an expense is necessary, optional or directly building future financial security.
Some expenses can legitimately sit somewhere different depending on your situation. Transportation is a good example. A basic method of getting to work may be a need, while an expensive upgrade may contain a discretionary component.
50/30/20 Budget Examples
Seeing the rule applied to different income levels can make the percentages easier to understand.
Example 1: $2,500 monthly take-home income
If essential expenses actually total $1,500, the person would already be 10 percentage points above the needs guideline. The solution does not have to be eliminating all wants. The person could temporarily reduce discretionary spending, look for ways to lower major fixed costs and decide how much of the remaining income should go toward savings or debt.
Example 2: $4,000 monthly take-home income
Example 3: $6,000 monthly take-home income
These examples show an important point: the percentage remains the same, but the dollar amounts change significantly as income changes. That is why the framework is best viewed as a proportional guide rather than a fixed spending plan.
50/30/20 Budget Calculator
Enter your monthly take-home income below to see the three target amounts under the traditional 50/30/20 framework.
This calculator provides a simple educational estimate. It does not determine whether a particular allocation is appropriate for your individual circumstances.
Does the 50/30/20 Budget Rule Actually Work?
The answer depends on what you expect the rule to accomplish.
If you expect 50/30/20 to automatically produce the perfect budget for every household, it will not. Real financial circumstances vary too much for one ratio to work identically for everyone.
But if you use it as a simple framework for evaluating your money, it can be very useful.
Why the 50/30/20 method can work well
- It is easy to remember.
- It creates broad spending boundaries.
- It makes savings part of the budget rather than an afterthought.
- It leaves room for discretionary spending.
- It can be used without tracking dozens of categories.
- It provides a simple starting point for beginners.
- It can reveal when fixed costs are consuming too much income.
Where the method can become difficult
- High housing costs can make 50% for needs unrealistic.
- Low income can leave very little room for discretionary spending.
- Large debt obligations may require a different priority structure.
- Irregular income makes fixed monthly percentages harder to apply.
- Major family responsibilities can change essential spending.
- Large short-term goals may require temporarily different percentages.
The most useful way to think about the rule is therefore as a diagnostic framework. If your numbers do not fit, ask why they do not fit and what you can realistically change.
What If the 50/30/20 Rule Doesn't Fit Your Income?
This is where many people make a mistake. They see that their needs are 65% of income and conclude that they are “bad at budgeting.”
A percentage guideline cannot change the price of housing, food, transportation, healthcare or other essential expenses by itself.
Instead, use the difference between your actual numbers and the guideline as information.
If needs are above 50%
Consider reducing optional spending first, then examine major fixed costs. Housing and transportation often deserve particular attention because relatively small changes in these large categories can have a bigger effect than eliminating many small purchases.
If wants are above 30%
Review recurring subscriptions, eating out, shopping, entertainment, convenience spending and lifestyle upgrades. Look for categories that provide little value relative to their cost.
If savings are below 20%
Do not assume that you must immediately reach 20%. Start by creating a sustainable savings habit. Even a smaller amount can establish the behavior, especially when income is limited.
If debt requires more than 20%
You may temporarily choose to direct more of your available income toward debt reduction. Once the debt burden decreases, your budget can change again.
How to Use the 50/30/20 Budget Rule Step by Step
Step 1: Calculate your take-home income
Start with the money you actually have available after taxes and required payroll deductions. If your income changes, use a realistic baseline rather than your highest month.
Step 2: Calculate your three target amounts
Multiply take-home income by 50%, 30% and 20%. These are your initial reference points.
Step 3: List your actual expenses
Review bank statements, payment records, bills and other financial information. Estimate irregular expenses instead of ignoring them.
Step 4: Classify your expenses
Place expenses into needs, wants or future-focused goals. If an expense is difficult to classify, ask whether it is necessary, optional or building financial security.
Step 5: Compare your actual numbers with the targets
Look for large differences. If needs are significantly above 50%, determine which major costs are responsible. If wants are high, identify discretionary categories. If savings are low, determine whether there is room to increase them.
Step 6: Adjust one or two important categories
Avoid trying to completely redesign your financial life overnight. Choose changes that are realistic and meaningful.
Step 7: Automate important savings
Where practical, schedule transfers toward important savings goals so they happen consistently rather than relying entirely on willpower.
Step 8: Review the budget monthly
Compare your planned percentages with actual spending. A budget becomes more useful when you learn from your previous months rather than repeatedly starting from zero.
How to Adapt the 50/30/20 Rule to Different Financial Situations
For people with low income
When income is limited, essential expenses can consume most of the available money. In that situation, forcing a strict 50% needs target may create an unrealistic plan.
Focus first on essential stability. Then look for sustainable ways to reduce costs, increase income, build a small emergency reserve and avoid adding expensive debt.
For high-income households
Higher income can make the framework easier to follow, but it can also create lifestyle inflation. A household may earn more and still struggle to save if discretionary spending rises at the same time.
In this situation, the 20% future-focused category may be viewed as a floor rather than a ceiling. If your goals are ambitious, you may intentionally save more.
For people with significant debt
Debt can change the priority order. Required minimum payments should be protected, while additional payments can be used to accelerate repayment when that is financially appropriate.
A person with expensive debt may reasonably choose a temporary allocation that places more than 20% toward debt reduction.
For families
Family budgets can contain expenses that are difficult to compress, including childcare, education, healthcare and transportation.
The framework can still provide a useful reference, but the actual percentages may need to reflect household responsibilities.
For irregular-income earners
Freelancers, contractors, commission earners and business owners may need a modified approach because monthly income is not predictable.
In such cases, consider building a buffer during stronger months and basing recurring expenses on a conservative income level.
Alternatives to the 50/30/20 Budget Rule
The 50/30/20 method is not the only way to budget. Different financial situations may call for different systems.
Zero-based budgeting
Zero-based budgeting gives every unit of available income an intentional purpose. It can be useful for people who want greater control over individual categories.
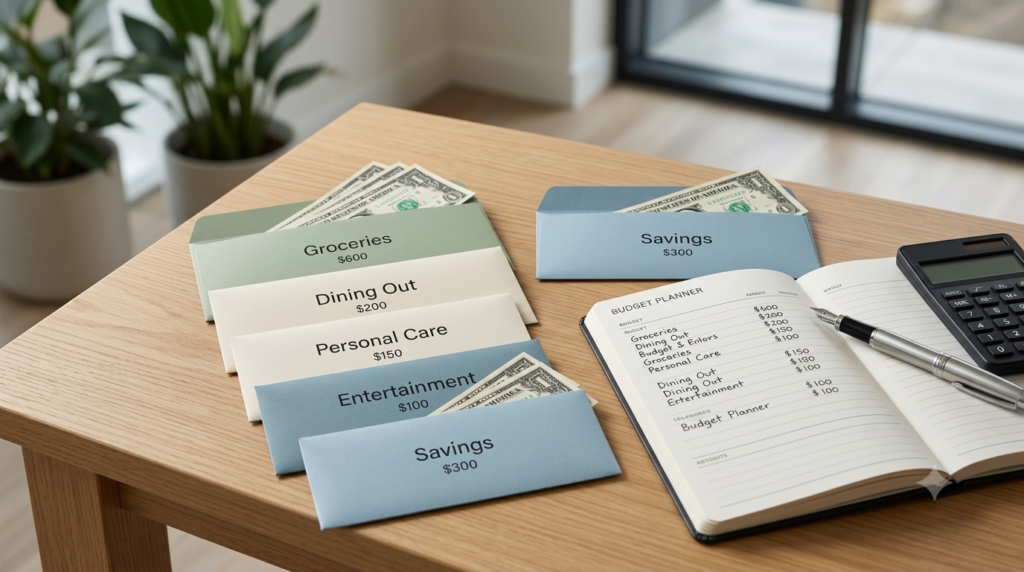
Envelope budgeting
Envelope budgeting creates spending limits for specific categories. It can be particularly useful when discretionary spending is the main challenge.
Pay-yourself-first budgeting
This approach prioritizes savings before discretionary spending. It can be useful for people who consistently spend whatever remains at the end of the month.
Cash-flow budgeting
Cash-flow budgeting focuses heavily on the timing of income and expenses. It can be especially helpful when bills and income arrive on different schedules.
The best method is the one you can understand, maintain and use to make better decisions.
Common 50/30/20 Budget Mistakes
1. Using gross income instead of take-home income
The traditional framework is generally based on money available after taxes rather than headline salary. Using gross income can make your spending targets appear larger than the money you actually have available.
2. Treating the percentages as mandatory
The framework is a guideline. If your situation requires different percentages, adjust them rather than abandoning budgeting altogether.
3. Calling every expensive purchase a need
A purchase does not become a need simply because you use it regularly. Consider whether the basic function is necessary or whether the specific version is a lifestyle preference.
4. Forgetting irregular expenses
Annual bills, repairs, gifts, school expenses and other predictable costs can destroy a monthly budget if they are ignored.
5. Treating the 20% as leftover money
If savings are whatever remains after spending, there may be nothing left. Give important future goals a deliberate place in the budget.
6. Ignoring expensive debt
Building savings while simultaneously carrying costly debt may require careful prioritization. The right balance depends on the debt terms, emergency needs and overall financial situation.
7. Creating a budget that is impossible to maintain
A theoretically perfect budget is not useful if you abandon it after two weeks. Sustainability matters.
50/30/20 Budget Checklist
50/30/20 Budget Rule FAQs
The 50/30/20 rule is a budgeting guideline that suggests using about 50% of take-home income for needs, 30% for wants and 20% for savings and additional debt repayment.
The traditional framework uses take-home or after-tax income as the starting point. This is the income available for your spending and financial goals after taxes and relevant payroll deductions.
Needs generally include essential housing, food, utilities, transportation, insurance, essential healthcare, required childcare and minimum debt payments, although the exact classification depends on your circumstances.
Wants generally include discretionary spending such as entertainment, dining out, hobbies, travel, subscriptions and non-essential purchases.
The 20% category can be used for savings, emergency funds, retirement, investments, financial goals and additional debt repayment beyond required minimum payments.
Adjust the framework to your circumstances. Review discretionary spending and major fixed costs, and determine whether your essential expenses can be reduced over time. The 50% target is a guideline, not a requirement.
Yes. The 20% figure is generally a target or starting point, not a maximum. If your essential expenses and lifestyle spending are comfortably below the other targets, saving more can support faster progress toward financial goals.
It can be a useful starting framework because it uses only three broad categories. Beginners can use it to understand their spending before deciding whether a more detailed budgeting method would be helpful.
It can be adapted, but variable-income households may need to use a conservative income baseline, build a cash buffer and adjust spending during higher- and lower-income months.
There is no single budgeting method that is best for everyone. The 50/30/20 rule is useful because it is simple, but other systems such as zero-based budgeting, envelope budgeting or cash-flow budgeting may be better suited to certain financial situations.
Is the 50/30/20 Budget Rule Right for You?
The 50/30/20 budget rule is valuable because it makes budgeting easier to understand. Instead of starting with dozens of categories, you begin with three major questions: how much of your income is required for needs, how much is being used for wants, and how much is being directed toward your future?
The percentages are not a test you have to pass. Your housing costs, income, family responsibilities, debt, location and financial goals may require a different allocation.
What matters most is that your spending is intentional. If your numbers do not fit the traditional 50/30/20 framework, use the difference to identify what needs attention rather than assuming the entire method has failed.
Start with your actual take-home income. Understand your essential costs. Put boundaries around discretionary spending. Give savings and debt reduction a deliberate place in your plan. Then review the results and adjust as your financial life changes.
A budget does not need to be perfect to be useful. It needs to help you make better decisions consistently.
Build a stronger budgeting system
The 50/30/20 framework is only one part of a complete money management system. Continue learning about practical budgeting and how to make a monthly plan that works in real life.